Avoid Exchange Rate Haircuts: UK Mortgages for Expats and Contractors
Yes, you can often get a UK mortgage using foreign currency income, but acceptance depends on lender policy, verifiable evidence and tax or remittance details. Rules under FCA MCOB and HMRC’s SA106 reporting requirements shape what lenders will accept. Before applying, check your documentation is complete and speak to a broker who handles these cases regularly.
TL;DR:
- Lenders typically convert foreign income at market rates, apply a lender-specific reduction, and stress test against currency and interest rate fluctuations.
- Residency and HMRC reporting practices, including UK tax filings and bank connections, significantly influence mortgage eligibility.
- Major, highly tradable currencies like dollars and euros are preferred, while volatile or controlled currencies are often excluded, especially for non-standard income types.
- Verifiable, consistent foreign income documentation such as payslips, employer letters, and tax returns are essential, with additional scrutiny for self-employed or contractor earnings.
- Specialized lenders or brokers are usually needed when income is in less common currencies, comes from complex sources, or involves non-resident applicants to improve approval chances.
Table of Contents
- How UK lenders assess foreign income
- Does your residency status affect mortgage eligibility?
- Which currencies and income types do lenders accept?
- What evidence do lenders need for affordability checks?
- Tax and remittance rules that affect foreign income borrowers
- Self-employed, contractor and CIS voucher evidence
- Preparing your application before you approach a lender
- Specialist lenders, private banks and when to involve a broker
- Weighing up the risk of borrowing against foreign income
- Getting support with your foreign currency income mortgage
- FAQ
- Sources
How UK lenders assess foreign income
When your income arrives in dollars, euros or any other non-sterling currency, a lender first has to convert it into pounds to work out what you can borrow. Most use a prevailing market exchange rate at the point of assessment rather than the rate on your payslip, which means the figure a lender sees can move from month to month depending on currency fluctuations.
Lenders then typically apply a reduction, often called a haircut, to the converted income before running affordability calculations. There is no fixed percentage set by the regulator. The FCA’s own rules require firms to assess affordability properly but stop short of mandating a universal discount or an approved list of currencies, so each lender sets its own buffer based on its appetite for currency risk.
On top of the conversion haircut, lenders stress test the mortgage against future interest rate rises, as they do for every borrower. For foreign income cases, many also factor in the possibility that the exchange rate could move against you, since a weaker pound against your income currency would make your mortgage payments harder to meet in real terms. This is why two applicants earning the same amount in different currencies can be offered very different loan sizes.
The regulatory backdrop matters here. Under MCOB 2A.3, where a regulated mortgage contract counts as a foreign currency loan, the lender must either give you a right to convert into an alternative currency or have other arrangements in place to limit your exchange rate exposure. Crucially, a standard sterling mortgage is not automatically treated as a foreign currency loan under these rules unless repayments are made wholly or partly from income or assets held in another currency. That distinction decides which protections apply to your case.
A few practical points follow from this:
- Lenders use their own conversion rate, not the rate quoted on international transfer apps or your bank statement.
- Expect an income reduction applied before affordability is calculated, with no standard percentage across the market.
- Stress testing covers both interest rate rises and currency movement, so your true borrowing capacity may be lower than a simple conversion suggests.
- Some lenders avoid foreign income cases entirely rather than build in currency risk tools, which narrows your choice of provider.
Does your residency status affect mortgage eligibility?
Your residency and immigration status has a direct bearing on how a lender views your application, often more than the income itself. UK residents who happen to earn in a foreign currency, perhaps through overseas contracts or international employers, are generally viewed more favourably than non-residents applying from abroad. Settled status, indefinite leave to remain or British citizenship tends to open up the widest range of lenders, while non-resident applicants face a smaller specialist pool.
Three things consistently strengthen a case regardless of where your income originates:
- Filing UK tax returns, even on overseas earnings, gives lenders a verifiable, HMRC-recognised record of your income.
- Holding a UK bank account that receives regular income deposits makes it easier for underwriters to trace and confirm cash flow.
- A UK residential address and a visible footprint, such as council tax records or utility bills, reassures lenders that you are a traceable borrower rather than a remote risk.
Lenders decline overseas income for operational reasons as often as for affordability ones. The FCA’s 2026 consultation on mortgage reforms notes that exchange rate exposure and operational complexity mean some lenders decline applicants even when their earnings would comfortably support the loan on paper. Verifying foreign documents, translating payslips and confirming overseas employers simply takes more work than a standard UK case, and not every lender’s underwriting team is set up for it. We cover more of the common refusal patterns in our piece on why high street banks decline foreign nationals, which is worth reading if you have already faced a knock back.
Which currencies and income types do lenders accept?
Lenders are far more comfortable with major, freely convertible currencies than with anything subject to exchange controls or thin trading. US dollars, euros, Swiss francs, Australian and Canadian dollars, and other G10 currencies are the ones most UK lenders will consider without hesitation, largely because exchange rates are transparent and funds move quickly and predictably.
Currencies that are harder to convert, subject to government controls, or prone to sharp volatility are treated far more cautiously, and some lenders rule them out altogether. This is less about prejudice against any particular country and more about operational risk: if a lender cannot be confident that funds will arrive reliably and at a predictable rate, they struggle to build the exchange rate protections that MCOB 2A.3 effectively requires.
The type of income also changes how it is treated:
- Salaried employment income is usually the easiest to verify, provided payslips and an employer reference are available.
- Pension income from overseas schemes is generally accepted but may need additional proof of continuity and source.
- Dividend income is scrutinised more heavily, since it can fluctuate year to year and depends on company performance.
- Rental income from an overseas property is often discounted further, reflecting void periods, maintenance costs and currency risk combined.
Delays in verifying foreign bank statements or employer confirmations are a common practical blocker, sometimes stretching an application timeline by weeks. Building that lead time into your plans, rather than assuming a UK-speed turnaround, avoids unnecessary frustration.
What evidence do lenders need for affordability checks?
Affordability assessment under MCOB 11 requires lenders to use verified income, committed expenditure and basic household costs, with independent evidence for every element of income. Self-certification, where a borrower simply states their earnings without supporting proof, is not permitted. For foreign income, that bar is higher still, since the underwriter has to be confident the figures translate accurately into pounds and reflect genuine, ongoing earnings.
A typical evidence set looks like this:
- Recent payslips covering at least three to six months, translated into English where necessary.
- An employer reference letter confirming your role, salary and currency of payment.
- Tax returns or their equivalent from your country of income, alongside your UK Self Assessment where applicable.
- Bank statements showing the income actually landing in your account on a consistent basis.
- Proof of any additional income streams, such as pension statements or dividend vouchers.
Lenders also build in your committed expenditure and basic living costs when calculating what you can afford, exactly as they would for a UK-only applicant. This means existing debts, childcare costs and regular outgoings all factor into the final figure, regardless of how strong your foreign income looks on its own.
Pro Tip: Prepare translated, dated and consistently formatted records before you approach a lender. Underwriters move faster when every document uses the same currency references and covers the same time period.
Tax and remittance rules that affect foreign income borrowers
HMRC’s SA106 guidance sets out how overseas income must be reported in UK pounds on your Self Assessment return, along with the conditions for Foreign Tax Credit Relief and the Foreign Income and Gains (FIG) regime. Getting this reporting right does more than keep you compliant. It gives a lender a clean, HMRC-recognised paper trail that supports the figures on your application, which makes your case easier to underwrite.
Where things get more complicated is for non-domiciled individuals using the remittance basis. HMRC’s internal manual on identifying remittances explains that foreign income used to service what it calls a relevant debt, which includes a mortgage secured on UK property, can be treated as a taxable remittance. In practice, this means that using offshore earnings to make your UK mortgage payments might trigger a tax charge you were not expecting, depending on how your finances are structured.
A few points worth bearing in mind:
- Converting and reporting overseas income in GBP on your SA106 return strengthens your evidence base for a mortgage application.
- Servicing a UK mortgage directly from offshore income can count as a remittance under HMRC rules, with tax consequences attached.
- Structuring the mortgage and the source of repayments without checking the remittance rules first can create liabilities that outweigh any convenience.
Given how easily this can go wrong, we always recommend speaking to a qualified tax adviser before finalising how your mortgage will be funded and repaid, particularly if you claim the remittance basis or hold income under the FIG regime.
Self-employed, contractor and CIS voucher evidence
Contractors and self-employed applicants earning in foreign currency face an extra layer of scrutiny, simply because there is no single employer confirming a fixed salary. Lenders want to see a consistent pattern of earnings rather than a single good month, and the evidence you present needs to demonstrate that pattern clearly.
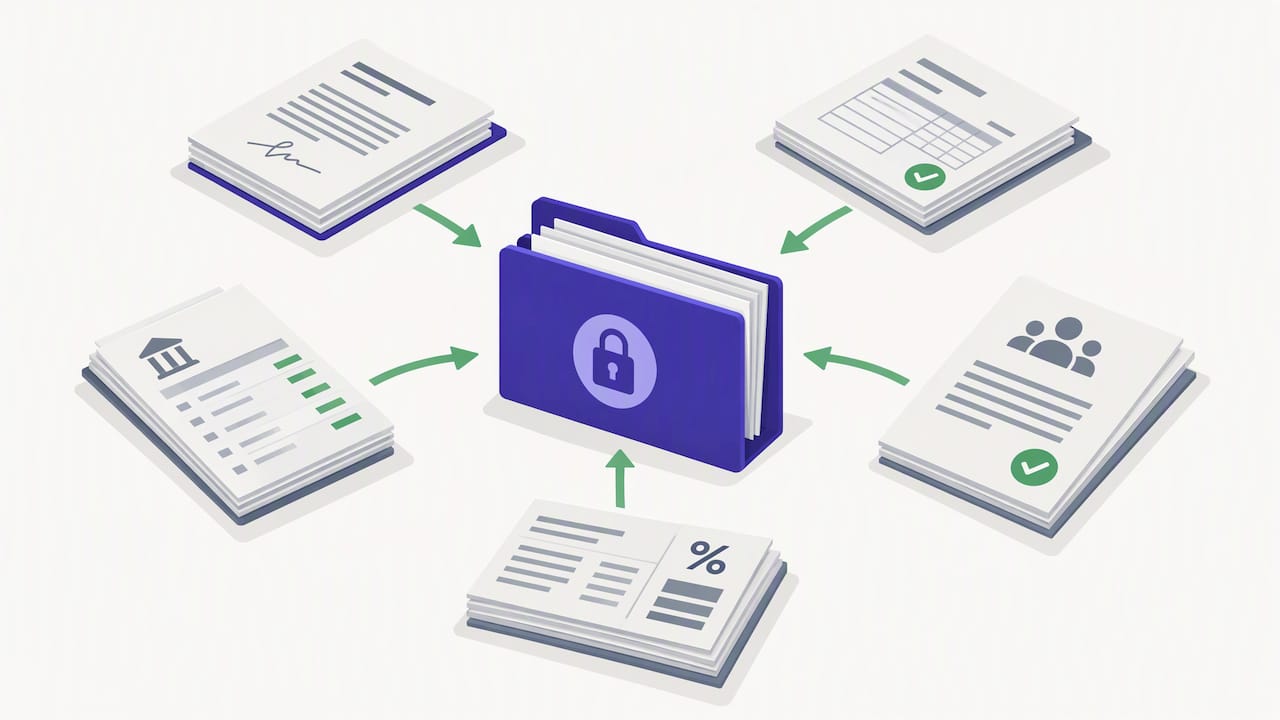
Acceptable proof typically includes signed contracts showing day rates or project fees, invoices issued and paid, bank statements showing those payments actually landing, and reference letters from agencies or end clients confirming the working relationship. For CIS subcontractors specifically, CIS vouchers and deduction statements provide a useful supplementary record, showing gross payments and tax already deducted at source, which helps a lender build a fuller picture of your true earning capacity rather than relying on net pay alone.
Where contractor income is paid in a foreign currency, combining day rate evidence with consistent banked income over several months, rather than just projected annual earnings, tends to carry more weight with underwriters.
Some practical points for contractors and CIS subcontractors:
- Keep signed contracts, invoices and CIS vouchers together as a single evidence pack rather than scattered records.
- A reference letter from your agency or main contractor, confirming day rate and typical working pattern, adds credibility.
- Manual underwriting, rather than automated scoring, is usually needed once income combines foreign currency and self-employed or CIS status.
Pro Tip: If your CIS income is paid in instalments or across multiple contracts, ask your accountant to produce a simple annual summary alongside your vouchers. It gives underwriters a single reference point instead of dozens of individual payments to reconcile.
A specialist broker is almost always worth involving at this stage, since few high street lenders have underwriting teams set up to read CIS vouchers alongside foreign currency conversions. We go into more depth on packaging day rate evidence in our guide on getting a UK contractor mortgage with bad credit, much of which applies equally to contractors with strong credit but foreign-paid income.
Preparing your application before you approach a lender
A little preparation before you submit anything can save weeks of back and forth once your application is live. The steps below cover the essentials.
- Check your credit file for errors and correct anything inaccurate well before applying, since lenders will view your history as part of the overall picture.
- Avoid making multiple mortgage enquiries that trigger hard searches, as these stay visible to lenders and can affect how your application is viewed; a soft versus hard credit check comparison explains the difference if you are unsure which applies.
- Gather certified translations of foreign documents and ensure payslips, contracts and tax returns are all dated consistently.
- Request confirmation letters from employers, agencies or tax advisers well in advance, since these often take longer to arrange than UK-based equivalents.
- Collect bank statements that clearly show your income flows and the source of your deposit, as lenders need to trace both.
- Ask a broker to run a soft eligibility check or a quotation search first, so you understand your realistic options before a formal application touches your credit file.
Our guide on what documents foreign nationals need for a mortgage sets out a fuller checklist if your case involves additional visa or residency paperwork.
Specialist lenders, private banks and when to involve a broker
Once your case involves foreign currency income, residency complexity or self-employed status together, the mainstream high street often narrows quickly. Specialist lenders, private banks and expat-focused mortgage providers tend to have underwriting processes built around exactly these situations, including buy-to-let products designed for overseas landlords. If you are considering a rental purchase while based abroad, our article on expat buy to let mortgage options walks through how those products typically work.
As independent, whole-of-market mortgage advisors, we work across specialist lenders as well as mainstream providers, which means we can match your foreign income profile to a lender whose policy actually fits your circumstances rather than guessing at the high street.
Some situations where a specialist route is usually the right call:
- Your income is paid in a currency that several mainstream lenders exclude from their policy.
- You combine foreign income with contractor or CIS self-employed status.
- You are a non-resident applicant without an established UK credit footprint.
- Your deposit originates from an overseas source that needs additional verification.
Weighing up the risk of borrowing against foreign income
Borrowing against foreign currency income makes sense when your earnings are stable, well documented and likely to continue for the term of the mortgage you want. It makes far less sense when your income is irregular, paid in a volatile currency, or dependent on a single contract that could end without notice. The stress testing lenders apply exists precisely because exchange rates and interest rates can both move against you at once, and a mortgage that looked comfortable at application can feel very different two years later.
A realistic deposit of a substantial amount tends to open up noticeably more lender choice for foreign income cases, partly because it gives the lender a bigger buffer against currency movement. One case that stays with us involved a contractor paid in euros across several short-term contracts, whose CIS vouchers and consistent banked income, once properly packaged, were enough to secure a mortgage that a mainstream lender had initially declined.
— Paul
Getting support with your foreign currency income mortgage
We work with subcontractors, self-employed applicants, contractors and foreign nationals across the local area, so foreign currency income cases are a routine part of what we do rather than an exception. We also arrange debt consolidation mortgages and CIS voucher mortgages for enhanced income for the self employed contractor, alongside standard contractor mortgages, which often sit alongside foreign income cases for the same client.
If you are not sure where you stand, we can run a free eligibility check against our whole-of-market panel before anything touches your credit file. Our services for foreign income and contractor cases include:
- Independent, whole of market mortgage advice across specialist and mainstream lenders.
- Self employed mortgage support, including contractor and CIS voucher evidence packaging.
- Affordability calculations and written confirmation so you know your realistic borrowing range before applying.
Get in touch to arrange a document review and a quotation search, and we will talk you through which lenders are likely to suit your income and circumstances.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can I get a UK mortgage with foreign income?
Yes, many UK lenders accept foreign currency income, though acceptance depends on the lender’s policy, the currency involved and how well your income is documented. Specialist and whole-of-market brokers can match your case to lenders with suitable experience, which widens your options considerably.
Can I get a foreign mortgage in the UK?
If you mean a mortgage on a UK property using income earned abroad, this is generally what’s meant by a foreign currency income mortgage, and it is available through specialist and some mainstream lenders. If you are looking to buy property overseas while living in the UK, that typically involves a different process through a lender or broker based in that country.
What salary do I need for a $500,000 mortgage in the UK?
There is no single published salary threshold for a specific loan amount, since affordability depends on your income currency, existing commitments, deposit size and the lender’s own stress testing under MCOB 11. A broker can run your figures against current lender criteria to give you an accurate, personalised estimate.
What is the 28/36 rule in the UK?
UK affordability assessments follow FCA rules under MCOB 11, which require lenders to verify income and factor in committed expenditure and basic living costs rather than applying a fixed income-to-debt ratio.
Sources
- FCA Handbook - MCOB 2A.3 Foreign currency loans
- Gov
- FCA consults on mortgage reforms to support first‑time buyers and underserved consumers (analysis)
Recommended
