Heavy Refurb Bridging for UK Investors: Budget a 10–15% Works Buffer
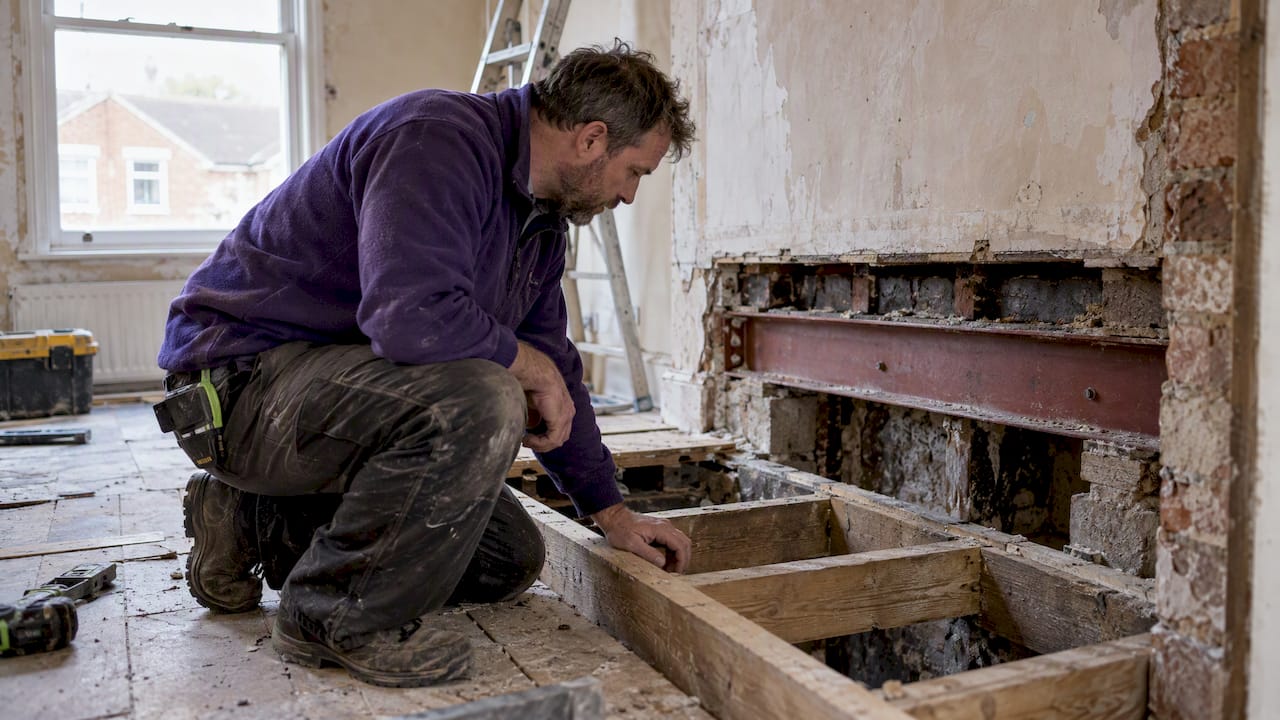
Yes, heavy refurbishment can be funded with short-term bridging, but lenders need a credible gross development value, a contractor-backed schedule of works and a believable exit before they will lend. We work with investors across East Sussex, and as a specialist broker, Prosper Home Loans can speed up approval once these three elements are in place.
TL;DR:
- Structural work, extensions, conversions, or changes of use can trigger development style underwriting, with lenders assessing projected finished value rather than simple comparables.
- Interest accrues only on funds already drawn, while staged releases may require monitoring inspections and incur additional fees.
- Some lenders may cover all build costs when sufficient equity exists in the property, but funding depends on the project’s value and evidence.
- A sale or refinance must be credible before approval; written lender confirmation outweighs verbal assurances, and delays may bring extension fees and reassessment.
Table of Contents
- What counts as heavy refurbishment or conversion
- What lenders and underwriters look for on heavy-refurb cases
- Costs, fees and timing you should budget for
- Planning the exit from the start
- Next steps: building a lender-ready pack
- How we approach heavy-refurb bridging cases
- We are an independent, whole-of-market mortgage and protection broker and we work with property investors on heavy-refurb and development-adjacent bridging. Because we search across the whole market rather than a single panel, we can match your project to a lender whose appetite fits your scope of works, not the other way round.
- FAQ
- Sources
What counts as heavy refurbishment or conversion
Lenders draw a sharp line between light cosmetic updates and heavy refurbishment, and knowing which side of that line your project sits on shapes every part of the application. Light refurbishment covers new kitchens, bathrooms, flooring and decoration, work a homeowner could organise without planning permission. Heavy refurbishment moves into structural and regulatory territory, and it changes how a lender values and monitors the loan.
Projects that typically count as heavy refurbishment include:
- Structural alterations such as removing load-bearing walls or underpinning
- Extensions, including rear, side return or additional storeys
- Loft or garage conversions that create new habitable space
- Change of use, such as converting a commercial unit to residential
- Splitting a single dwelling into multiple flats, or merging units
Once a project needs planning permission or building control sign-off, the underwriting profile shifts. Lenders start asking for evidence that the finished scheme will achieve the projected value, which means valuers often apply a development-style approach rather than a simple market valuation. The RICS guidance on valuation of development property sets out how gross development value and the residual method are used for exactly this kind of project, and it explains why a straightforward comparable valuation often will not satisfy a lender once works become structural.
What lenders and underwriters look for on heavy-refurb cases
Heavy-refurb bridging sits closer to development finance than to a standard bridge, and lenders underwrite it accordingly. Approval, pricing and the maximum advance all depend on the strength of the evidence you bring to the table.
Underwriters typically work through the following in order:
- A RICS or IVS-compliant valuation that stress-tests the projected gross development value rather than accepting your own figure
- A detailed schedule of works with contractor quotes, a realistic timescale and a contingency of around ten to fifteen percent built in
- A monitoring regime, usually a surveyor inspecting progress before each staged drawdown is released
- Security and loan-to-value positions calculated both before and after the works, since some lenders will fund up to 100% of build costs where there is sufficient equity in the existing asset
- Evidence of a workable repayment strategy, which the FCA’s mortgage conduct rules require lenders to assess properly before lending
On that last point, FCA Handbook MCOB rules require lenders to be satisfied that your repayment route, whether sale or refinance, is genuinely credible before the loan is advanced. This is not a box-ticking exercise; it shapes the paperwork lenders expect from you at application stage.
Pro Tip: Get your schedule of works priced by your contractor before you approach a lender, not after; an underscored budget is one of the most common reasons heavy-refurb applications stall.
Costs, fees and timing you should budget for
Interest on heavy-refurb bridging is usually quoted as a monthly rate, and it accrues on each tranche from the date it is drawn rather than on the full facility from day one. That matters for cashflow, because staged drawdowns mean you are not paying interest on money you have not yet used.
Beyond interest, expect to budget for:
- Lender arrangement fees, typically charged as a percentage of the loan
- Legal fees for both your solicitor and the lender’s solicitor
- Valuation fees, often higher than a standard valuation given the development-style assessment required
- Monitoring surveyor fees, charged each time a drawdown inspection is carried out
- Broker fees, which we set out transparently before any application proceeds
A key underwriting safeguard to plan around is the GDV haircut. Industry analysis of refurbishment bridging notes that lenders commonly stress-test your projected gross development value and may apply a reduction of between ten and fifteen percent when calculating how much they are prepared to advance. Building that haircut into your own budgeting before you apply avoids an unpleasant surprise mid-project.
Timescales vary by lender and case complexity, but a well-prepared application with a regulated bridging loan broker can move from application to first drawdown within a matter of weeks rather than months. Site inspections for subsequent drawdowns are then scheduled around your build programme, and the overall loan term is set to cover the works plus a reasonable buffer for sale or refinance, often supported by professional aerial photography and inspection services to monitor progress accurately. For a sense of where bridging rates sit in the current market, it helps to compare quotes before committing to a lender.
Planning the exit from the start
Your exit strategy should be decided before you apply, not worked out once the build is finished. Lenders need to see it clearly mapped, and the FCA requires them to assess whether it is realistic.
The three common routes are:
- Sale of the finished property, which works well when there is a clear comparable market and no reliance on a buyer chain
- Refinance to development exit finance, useful when you want to hold the asset at practical completion while a term loan is arranged, covered in more detail in our guide to development exit finance
- Refinance to a buy-to-let mortgage or standard term mortgage, suited to investors planning to let or retain the property long term
Under FCA MCOB rules, a lender must be satisfied that a mainstream mortgage lender would actually be willing to take over the debt, or that a sale is genuinely achievable, before accepting that repayment route. A robust agreement in principle or a firm mortgage offer carries far more weight than a verbal assurance. If your exit slips, most bridging lenders will consider an extension, though this usually comes with additional fees and a fresh assessment of your progress and remaining timescale, so it pays to flag any delay early rather than at the deadline.
Next steps: building a lender-ready pack
Getting organised before you approach a lender saves weeks later in the process. We recommend working through this sequence:
- Pull together your schedule of works, itemised contractor quotes, a realistic programme and a contingency of ten to fifteen percent
- Order a development-style valuation early, and gather contractor references where you can
- Speak to a specialist broker to test lender appetite and understand what written confirmation you will need
- Budget time and cost for monitoring fees, and factor in planning or building control sign-off timescales before setting your programme
A clear, contractor-backed pack is the single biggest factor in how quickly a heavy-refurb case moves from enquiry to drawdown.
How we approach heavy-refurb bridging cases
Heavy-refurb and contractor-led projects need documentation that goes beyond a standard bridging application, and that is where our experience with CIS subcontractor income and self-employed case structuring proves useful. We compile valuation evidence, liaise directly with surveyors on monitoring schedules, and structure staged drawdowns so your cashflow matches your build programme rather than working against it. Clients typically move from first enquiry to a clear lender decision once their schedule of works and contractor evidence are in order.
— Paul
We are an independent, whole-of-market mortgage and protection broker and we work with property investors on heavy-refurb and development-adjacent bridging. Because we search across the whole market rather than a single panel, we can match your project to a lender whose appetite fits your scope of works, not the other way round.
For CIS subcontractors and self-employed investors, we also structure applications using CIS voucher income to demonstrate enhanced earnings, and we arrange contractor mortgages alongside bridging exits. Where a heavy-refurb project has left you juggling multiple debts, we can also discuss debt consolidation mortgages as part of your wider refinancing plan.
When you contact us, we will:
- Run an initial affordability check and confirm likely lender appetite for your project
- Build a structured application pack, including written confirmation where a lender requires it
- Set out our fees clearly before any application proceeds, in line with our mortgage advice fee structure
- Keep you updated at each stage from enquiry through to drawdown
If you are planning a heavy refurbishment or conversion, visit our specialist lending services to request a call back and talk through your project with us directly.
FAQ
What is the difference between bridging finance and a standard mortgage?
Bridging finance is a short-term loan, usually repaid within months rather than years, designed to cover a gap such as a refurbishment or purchase before longer-term finance or a sale completes. A standard mortgage is a long-term loan secured against a property you intend to hold, assessed on ongoing affordability rather than a short-term exit plan.
Can I get 100% funding for heavy refurbishment costs?
Availability depends on your project’s gross development value and the strength of your schedule of works.
What red flags do lenders watch for on heavy-refurb applications?
Lenders are cautious about under-scoped budgets with no contingency, missing contractor quotes, unrealistic build timescales and an exit strategy that relies on an optimistic sale price or an unconfirmed refinance. A pack lacking a RICS development-style valuation is also commonly flagged for further review.
Does a heavy-refurb project affect my ability to service other loans?
Lenders assess affordability across your whole portfolio, so an active heavy-refurb project with monthly interest payments can affect how much they are willing to lend elsewhere until the bridge is repaid. This is one reason a clear, evidenced exit plan matters under FCA MCOB, since lenders want confidence the facility will be cleared on schedule.
How do specialist bridging lenders differ from mainstream lenders for heavy refurb?
Specialist bridging lenders are set up to assess development-style valuations, monitor staged drawdowns and lend against projects mid-construction, which mainstream mortgage lenders generally will not do. Mainstream lenders typically only enter the picture once the refurbishment is complete and the property is ready for a standard term mortgage or buy-to-let remortgage, as outlined in MoneyHelper’s buy-to-let guidance.
Sources
- FCA Handbook - MCOB 11.6 Responsible lending and financing
- RICS — Valuation of development property
- Forbes Advisor — Bridging loans for refurbishment (UK)
Recommended
