Gifted Deposit Rules for UK Mortgages Explained

A gifted deposit is money from a family member that you put towards your home, and UK lenders will accept it if it is a true gift: not a loan, no repayment expected, and no claim on the property for the giver. Each lender sets its own detail, so the paperwork and limits differ. We are a local mortgage broker serving Hastings, Eastbourne, Hailsham, Bexhill-on-Sea and the rest of East Sussex, and this guide sets out the rules in plain English so you and your family know what to prepare before you apply.
TL;DR
- A gift must be non-repayable. Lenders ask for a signed letter confirming no repayment is expected and that the giver has no interest in the property.
- Most lenders want to see where the money came from, and the giver’s ID, so start gathering documents early.
- Limits vary by lender: who counts as family, how many givers, and how large the loan can be.
- Gifts from abroad usually mean longer bank statement histories and extra checks.
- The giver should think about inheritance tax, especially if they will keep living in or benefiting from the property.
Table of Contents
- What makes a gift a gift
- Who can give you a deposit
- The giver must have no stake in the home
- What the gifted deposit letter should say
- Source of funds and ID checks
- Gifts from abroad
- Tax points for the giver
- If you are self-employed or work under CIS
- Getting the order right
- How we can help
- Our view on family help
- FAQ
- Sources
What makes a gift a gift
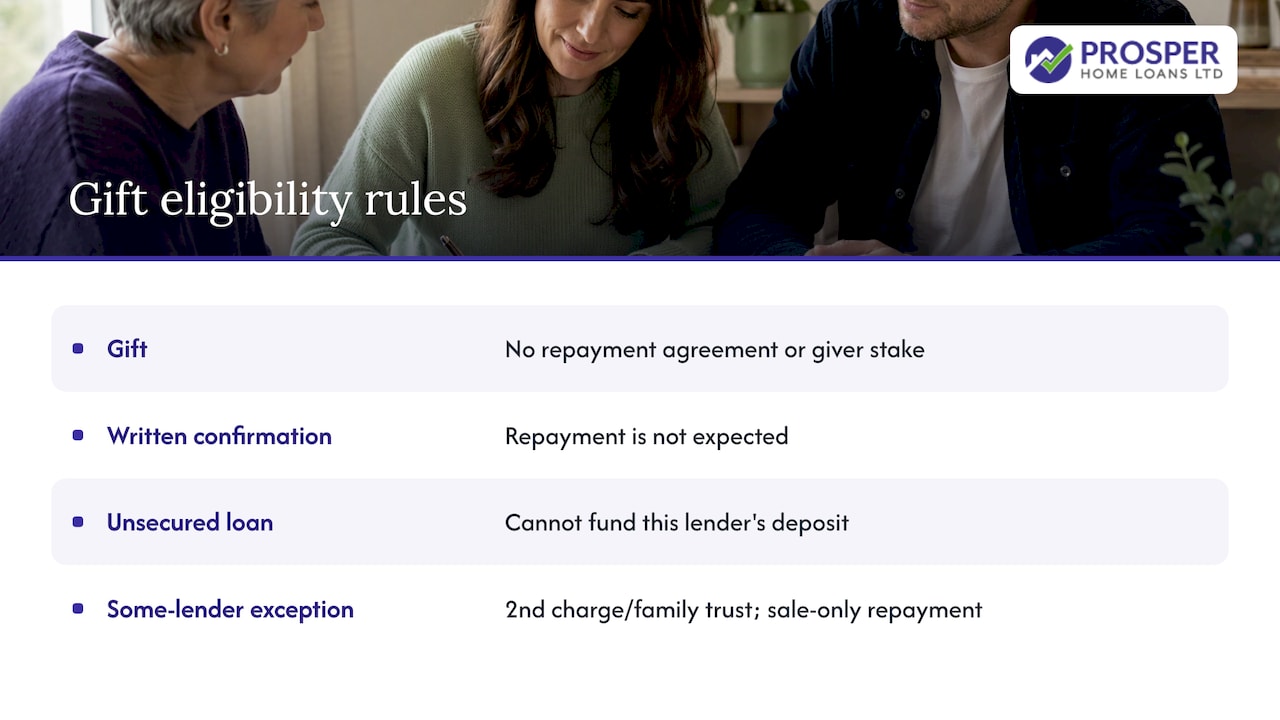
A gifted deposit is a cash gift from a relative used for part or all of your deposit. One major lender’s guidance says it must not be a loan, with no agreement to repay it, and the giver cannot have a stake in the home. You also have to confirm in writing that repayment is not expected.
Another lender says you cannot use an unsecured repayable loan towards its mortgage deposit. So a “gift” that your parents expect back when they need it, or when you sell, will not qualify.
There is one exception some lenders allow. A building society says anyone over 18 can give a gift with no conditions attached, with the only exception being a gift secured by a second charge or family trust where the sole condition is repayment on sale. Not every lender takes this route, so ask before you build a plan around it.
Who can give you a deposit
There is no single UK-wide list. Lenders decide for themselves. As examples:
- One lender accepts gifts from parents, step-parents, in-laws, grandparents, aunts and uncles, siblings, children and civil partners.
- Another says gifted residential deposits must come from immediate family, can come from up to three different sources, and are not accepted on loans over £500,000. That is one lender’s October 2026 document, so treat it as an illustration rather than a universal limit.
A gift from friends, an employer or the seller is a different matter and is often refused. The same Kensington document says vendor deposits are unacceptable.
If two grandparents and a parent want to contribute, the number of givers matters. This is a common reason to check lender criteria before you choose a mortgage, not after.
The giver must have no stake in the home
This is the rule that catches families out. One lender will not accept a gifted deposit if it is protected by a deed of trust, if the giver will live in the property without being on the mortgage, or if they hold a beneficial ownership interest.
In practice: if your parents hand over £20,000 and have it written down that they own a share of the house, that is not a standard gifted deposit. If they want to be on the title, a different structure may be needed. Our article on gifted equity mortgages covers that route.
What the gifted deposit letter should say
The letter is the document everyone asks about. A lender’s guidance says it typically includes the names and addresses of buyer and giver, their relationship, the amount and source of the gift, confirmation it will not be repaid and that the giver has no stake in the property.
A checklist for your family:
- Full names and addresses of the giver and you.
- How you are related.
- The exact amount.
- Where the money came from, such as savings, sale of a property or an inheritance.
- A statement that no repayment is expected.
- A statement that the giver makes no claim on the property.
- Signatures from both of you.
Most lenders have their own form. One building society asks for its Gifted Deposit Form for gifts of £10,000 or more, so use the lender’s version where there is one, rather than a generic template.
Source of funds and ID checks
Expect your conveyancer to ask for proof of identity from the giver. One lender explains this is typically a photo ID plus two different proofs of address, and that the conveyancer must check where the money came from to meet Anti-Money Laundering Regulations. Acceptable origins include the sale of a house or asset, shares, a pension or an inheritance.
Timing matters too. One lender asks for statements showing where the money came from if the gift arrived within the last 12 months, while a gift received over 12 months ago can be treated as a standard deposit.
So, a good habit is to ask the giver to keep recent statements and not to move money between several accounts first. A clean, simple trail is easier to explain.
Gifts from abroad
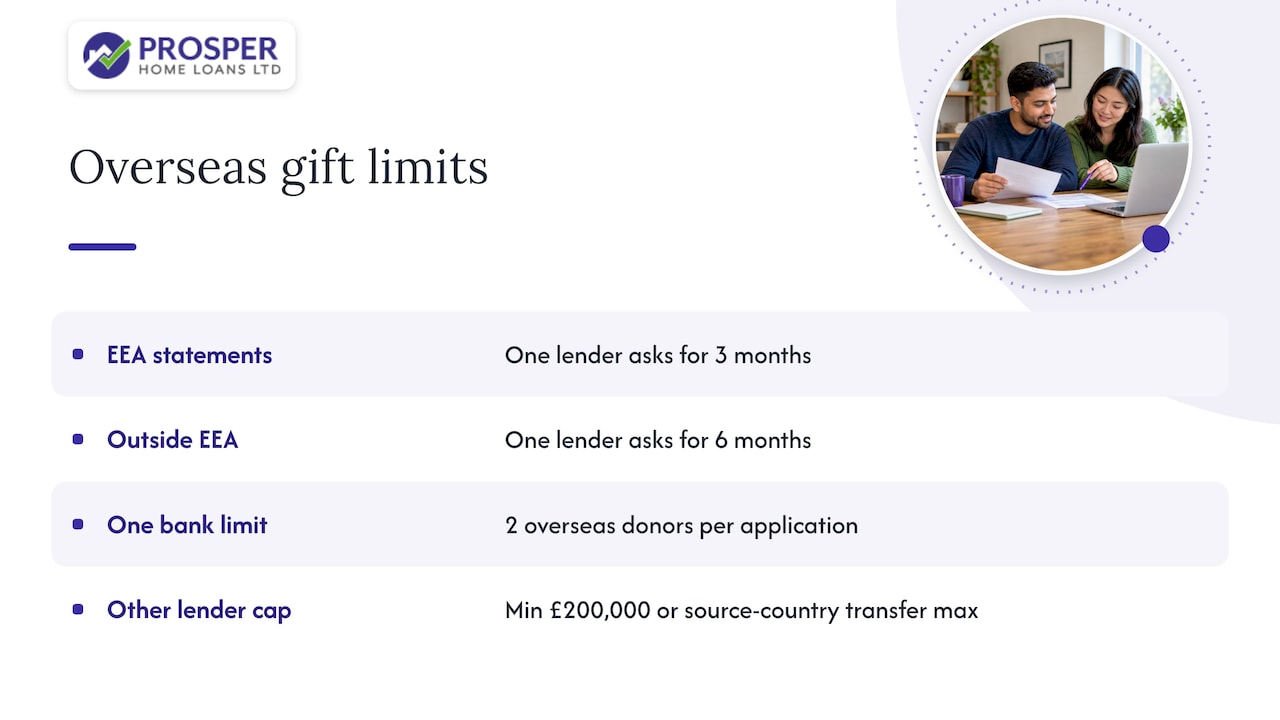
If a relative overseas is helping, expect extra steps. For gifts from outside the UK, one lender asks for three months of the donor’s bank statements if the money comes from within the EEA and six months if it comes from outside it.
Other lenders go further. One bank’s guidance (version 7.2, August 2026) says it may accept an overseas donor subject to additional checks, takes a maximum of two overseas donors per application, and asks for ID, address evidence, certified translations and a signed declaration. Another lender caps overseas gifts at the lower of £200,000 or the source country’s maximum foreign currency transfer, requires the money to arrive in a UK bank account in sterling, and does not accept gifts from certain high-risk jurisdictions.
If you are an NHS or healthcare worker from overseas, or a visa holder buying in the UK, our guides on documents foreign nationals need and mortgage eligibility for visa holders are a good next read.
Tax points for the giver
There is no tax for you as the person receiving a gift in the way you would pay income tax on earnings. The giver should think about inheritance tax. HMRC’s manual states that inheritance tax can be charged on lifetime gifts made within seven years of the giver’s death, or where the giver keeps benefiting from what they gave away, for example by living in a house they have given away.
HMRC also explains that where a giver keeps a benefit at death, the gifted property is treated as part of their estate. That is another reason the giver should not move into the property without proper advice. Your family should speak to a tax adviser or solicitor about their own position.
If you are self-employed or work under CIS
A gift does not replace affordability. Lenders still assess your income, and a bigger deposit can widen your choices but does not guarantee approval. If you are a CIS subcontractor, sole trader or company director, you will also be asked to show that your own savings are genuine. Our guide on proving your deposit as a self-employed buyer covers the paperwork.
Where your income is assessed, some lenders may use gross CIS earnings, subject to their criteria. That is about how affordability is calculated and does not change what you actually earn or guarantee a higher loan.
Getting the order right
The sequence that avoids delays:
- Talk to a broker before you choose a lender, so the givers, amounts and countries fit that lender’s criteria.
- Agree who is giving what, and make sure everyone understands it is not repayable.
- Collect ID, proof of address and bank statements for each giver.
- Complete the lender’s gift form and tell your conveyancer early.
- Keep the money in an account that shows a clear trail until it is needed.
How we can help
We are a local, independent mortgage and protection advice firm in St. Leonards-on-Sea, helping buyers across Hastings, Bexhill-on-Sea, Eastbourne, Hailsham and East Sussex, and clients across the UK. We can look at your deposit, the givers and your income, including self-employed and CIS income, and explain which lenders’ criteria may suit your circumstances. Our first-time buyer mortgage page is the place to start.
We support clients from first enquiry through to completion. Outcomes depend on your circumstances and lender criteria, and nothing here promises approval.
Our view on family help
Families often tell us the hardest part is not the money, it is not knowing what the lender will ask for. A parent may be ready to help, but the letter, the statements and the source of funds can feel like an interrogation if no one has explained why they are needed.
Our approach is to make mortgages easier to understand. We explain the costs and risks clearly, check lender criteria before you commit to a product, and support you through to completion and future reviews. That matters most when income is not a standard payslip, as with CIS subcontractors, the self-employed and company directors.
If your family is planning to help, talk to us before the money moves.
Paul McMath CeMAP CeRER
FAQ
Is there a legal limit on how much family can give for a deposit?
The research we have found shows no single legal cap on the gift for mortgage purposes. Limits come from individual lenders, such as the maximum loan size or number of givers. The giver should also consider inheritance tax, as above.
Can more than one family member contribute?
Often yes, but it depends on the lender. One lender’s documents allow gifts from up to three sources, while another limits overseas donors to two per application. Check before applying.
Do I need a gifted deposit letter?
Yes, in nearly all cases. It confirms the money is a gift, is not repayable and gives the giver no claim on the property. Many lenders have their own form, which you should use.
Can a relative abroad gift me a deposit?
Sometimes. Lenders usually ask for more bank statements, ID, translations where needed and a UK sterling account, and some refuse certain countries. A broker can check this against lender criteria first.
Sources
- Gifted deposit guidance for mortgages (lender guide)
- Using a gift as a deposit (lender guide)
- Gifted deposits guide (lender guide)
- Foreign and gifted deposits (lender help page)
- Proof of deposit requirements guide, June 2025
- Source of deposit information, October 2026
- Gifted deposit guidance V7.2, August 2026
- HMRC Inheritance Tax Manual IHTM14001
- HMRC Inheritance Tax Manual IHTM47060
Recommended
- Avoid Tax Traps: UK Lenders and Solicitors on Gifted Equity Mortgages
- Proving Your Deposit as Self-Employed Mortgage Applicants
- Remortgage to Raise a Deposit: 3 Adviser Checks UK Homeowners Must Do
- New Build Mortgages When Couples Put Down Different Deposits
This article provides general information and is not a personal mortgage recommendation. Mortgage availability and eligibility depend on your circumstances and lender criteria. Rates and criteria can change. We will explain any applicable fees before you commit. Think carefully before securing other debts against your home. Consolidating debts over a longer term may reduce your monthly payments but increase the total amount you repay. Your home may be repossessed if you do not keep up repayments
