Decreasing vs Level Term Cover: Which Suits Your Mortgage?

The difference comes down to what the policy pays out. Level term cover pays the same amount whenever you claim during the policy. Decreasing term cover pays less each year. In the UK, decreasing cover is usually matched to a repayment mortgage. Level cover is the better fit when the debt, or the income your family needs, does not shrink over time.
Below we explain how each works, when each makes sense, and what self-employed people and CIS subcontractors should think about before choosing. This is general information, not personal advice. The right policy depends on your mortgage, your family and your health.
TL;DR
- Level term: the amount paid out stays fixed for the whole term. Premiums are fixed unless the policy is reviewed.
- Decreasing term: the amount paid out falls steadily, in line with a repayment mortgage, while the premium stays the same. It is generally cheaper than level term.
- Repayment mortgage: decreasing cover is the usual match. Interest-only mortgage: the debt does not fall, so level cover is usually the closer fit.
- Self-employed: life cover pays on death only. Income protection covers you if illness or injury stops you working.
- Neither is better in every case. It depends on what you are protecting.
Table of Contents
- How level term cover works
- How decreasing term cover works
- Side by side
- Which one for which mortgage?
- What self-employed people and subcontractors should weigh
- Other points before you buy
- Our view as a broker
- Talk to a local adviser
- FAQ
- Sources
How level term cover works
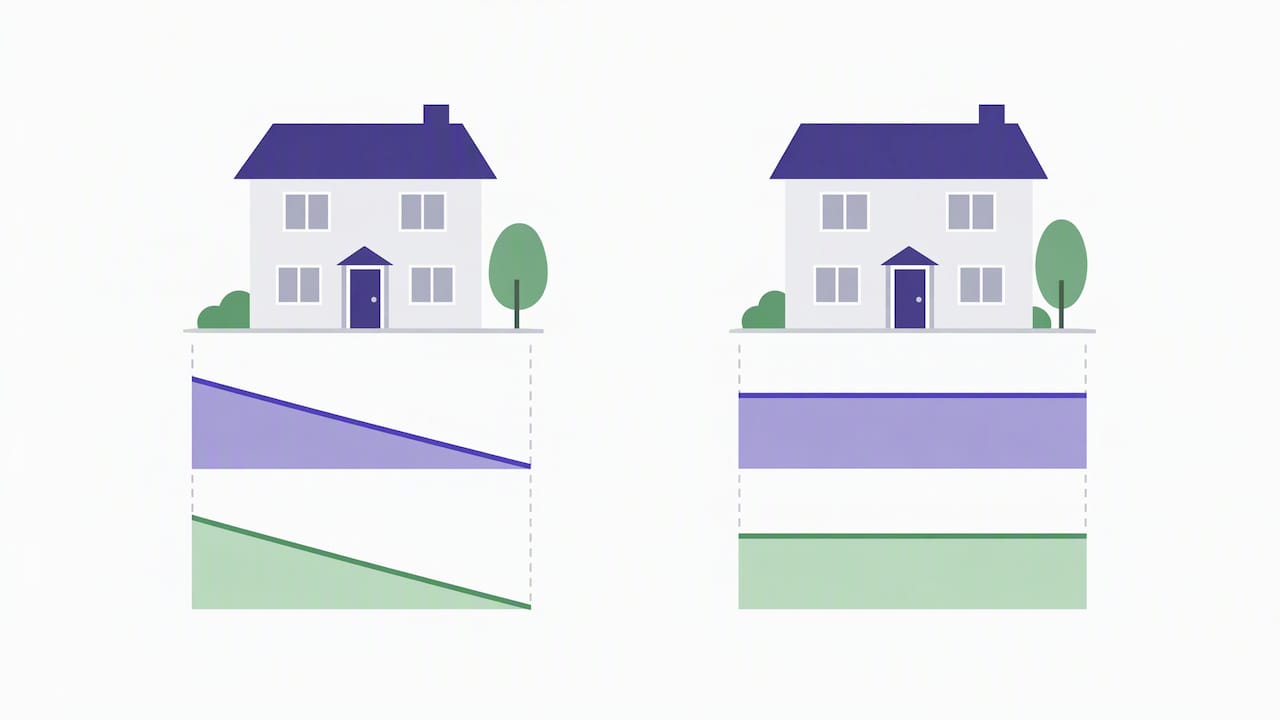
You choose a sum assured and a term, for example £250,000 over 25 years. If you die during the term, the policy pays that amount. It does not matter whether that is in year 2 or year 24.
The ABI explains that cover stays the same and premiums are fixed unless the policy is reviewed. Reviewable policies tend to be cheaper to buy, but the premium can change at review, so check which type you are being quoted.
Level cover suits:
- an interest-only mortgage, where the balance stays the same until the end of the term
- a family that needs a lump sum to replace income, not just clear a loan
- other debts or costs that will not shrink, such as childcare or a business loan
How decreasing term cover works
With decreasing term, the sum assured reduces every year to the end of the term. The ABI glossary describes this as reducing in line with a repayment mortgage, while the premium stays the same.
Because the insurer’s possible payout shrinks over time, decreasing term is generally less expensive than level term. The FCA’s market study lists both as the most common types of term assurance in the UK.
The idea is simple. On a repayment mortgage, you owe less each year. Cover that falls with the balance should be enough to clear the loan if the worst happens, without you paying for cover you no longer need.
Side by side
| Level term | Decreasing term | |
|---|---|---|
| Payout over time | Stays the same | Falls each year |
| Premium | Fixed unless reviewable | Stays the same |
| Typical cost | Higher | Generally lower |
| Best matched to | Interest-only mortgages, income replacement | Repayment mortgages |
| Main risk | Paying for more cover than a falling debt needs | Cover may fall short if your needs grow |
Which one for which mortgage?
Repayment mortgage
Decreasing term is the traditional choice. If your only aim is to clear the mortgage for your family, it can do that at a lower cost. Ask the adviser how the policy’s reduction compares with your actual repayment schedule, because the two may not match exactly.
Decreasing is not always enough. If your partner would also need to replace your income, or you want a cushion for other bills, a level policy, or a level policy alongside a smaller decreasing one, may be worth pricing.
Interest-only mortgage
Your balance stays the same, so cover that falls would leave a gap. Level term is usually the closer fit. Our guide to interest-only residential mortgages covers what lenders expect to see.
Part repayment, part interest-only
Some borrowers split the loan. Each part may need different cover, or one level policy for the interest-only portion plus a decreasing one for the repayment portion.
When your mortgage changes
Remortgaging, borrowing more or moving can all change what you need. The FCA’s market study makes clear these are separate products from your mortgage, so a policy bought years ago may no longer fit. If you are remortgaging, it is a good moment to review it.
What self-employed people and subcontractors should weigh
If you work under CIS or run your own business, you probably have no employer death-in-service benefit and no company sick pay. That changes the picture in two ways.
- Life cover is only part of it. Life insurance pays out on death. Income protection pays a monthly income if you cannot work through illness or injury, which is often the more likely problem for someone in a physical trade.
- Be realistic about the budget. MoneyHelper says that if you cannot afford everything, prioritise and consider a lower level of cover, because some protection can be better than none.
If you are a limited company director, there may also be a tax-efficient route through your business. See our piece on the relevant life policy for directors.
If you are preparing a mortgage application as a subcontractor, our list of documents subcontractors need for a mortgage is a useful checklist.
Other points before you buy
- You do not have to buy from your lender. MoneyHelper notes that you can shop around for cover rather than taking the one your mortgage lender offers.
- Life cover is not a legal requirement for a mortgage. Buildings insurance is different: it is usually a condition of the mortgage.
- Terminal illness cover. MoneyHelper says many good term policies include a terminal illness benefit, usually where life expectancy is under 12 months. Check the wording.
- Health and age matter. The younger and healthier you are when you apply, the lower your premium is likely to be, according to the FCA’s market study.
- Trusts. Writing a policy in trust can let the payout go straight to your beneficiaries without waiting for probate, as MoneyHelper explains.
Our view as a broker
Most people who ask us about this are really asking a different question: what would my family need if I were not here? The mortgage is one part of that answer.

We start with your loan type and then look at the rest. Who depends on your income? How long would savings last? For CIS subcontractors and the self-employed, we also ask what happens if you are off work for six months, because that is a more common risk than death.
We would rather you had a modest, well-matched policy you can keep paying than a big one you cancel after a year. We do not promise any outcome on price or acceptance. Premiums and underwriting depend on your age, health, occupation and the insurer’s criteria.
— Paul McMath CeMAP CeRER
Talk to a local adviser
Prosper Home Loans is based in St. Leonards-on-Sea and advises clients in Hastings, Bexhill-on-Sea, Eastbourne, Hailsham and across East Sussex and the UK. We can review your mortgage and your life insurance, critical illness and income protection options together, so cover matches the loan you actually have.
FAQ
Is decreasing or level term better for a repayment mortgage?
Decreasing term is designed for this, since the cover falls as the loan does and is generally cheaper. Level term can still make sense if you also want to protect your family’s income or other debts. The right choice depends on your circumstances.
What is the point of decreasing term insurance?
It covers a debt that shrinks, usually a repayment mortgage, at a lower cost than fixed cover. You pay a steady premium while the payout reduces in step with the balance.
Is it worth having life insurance if you don’t have a mortgage?
Possibly. Life insurance is not only for mortgages: it can help if others rely on your income or share your debts. If nobody depends on you financially, you may not need it. Income protection may matter more for self-employed people.
What happens when a term policy ends?
Term cover ends at the end of the term and usually pays nothing if you are still alive. That is why the term should run at least as long as your mortgage, or as long as your family needs the protection.
Sources
- ABI: Term insurance
- ABI: Decreasing term insurance glossary
- ABI: What insurance do I need if I get a mortgage?
- FCA: MS24/1.3 Structure of the UK pure protection market
- MoneyHelper: What is life insurance?
- MoneyHelper: How to know what kind of protection insurance you need
Recommended
- New Build Mortgages When Couples Put Down Different Deposits
- Mortgage Deposits by Job Type: What to Expect
- Mortgage Affordability Calculator or AIP First?
- Ex Council Flat Mortgages for UK Buyers: How Discounts Affect Lenders
This article provides general information and is not a personal mortgage recommendation. Mortgage availability and eligibility depend on your circumstances and lender criteria. Rates and criteria can change. We will explain any applicable fees before you commit. Think carefully before securing other debts against your home. Consolidating debts over a longer term may reduce your monthly payments but increase the total amount you repay. Your home may be repossessed if you do not keep up repayments
