Serviced Accommodation Mortgages in the UK: How They Work

A serviced accommodation mortgage is not one standard product. Lenders usually treat serviced accommodation as a specialist case, sitting between a holiday let and a standard buy-to-let, and each lender sets its own rules. Which lender suits you depends on the property, the letting model, your experience and how the rent is assessed. We are a local, independent mortgage broker in Hastings and across East Sussex, and we arrange this kind of finance for landlords and investors, including self-employed and limited company clients.
TL;DR
- Lender appetite is product-specific: some buy-to-let ranges accept serviced accommodation and some do not.
- Lenders assess rent after costs and a stress test, not your projected nightly revenue.
- Expect a larger deposit than a standard buy-to-let, plus proof of where the money came from.
- Check planning, the lease, insurance and your mortgage terms before you buy or let.
- Nothing here is a promise of approval or a particular rate. Criteria change, so speak to an adviser about your case.
Table of Contents
- What a serviced accommodation mortgage actually is
- How lenders assess the rent
- Deposits, rates and fees
- What to have ready
- Planning, lease and insurance checks
- How we help
- Our view
- FAQ
- Talk to a local adviser
- Sources
What a serviced accommodation mortgage actually is
Serviced accommodation means a furnished property let for short stays, often to contractors, business travellers or families between homes. There is no legal definition of it, and whether it counts as ordinary housing or hotel-type use for planning depends on the pattern of occupation, such as how often guests arrive and leave.
That lack of a definition is why lenders differ. A holiday let mortgage is usually written for property let furnished to holidaymakers, and a property generally needs to be available for at least 210 days a year to qualify as a holiday let rather than a buy-to-let. Serviced accommodation often sits awkwardly between the two. Some lenders place it in a holiday-let or specialist range. Others decline it altogether: one buy-to-let lender states that its range does not currently accept serviced accommodation.
If you already have a standard buy-to-let mortgage, do not simply start letting short term. Most standard buy-to-let terms limit use to a longer residential tenancy, and short lets without consent can breach the mortgage conditions. You need the lender’s written consent first, or a mortgage that allows it.
How lenders assess the rent
This is where many investors are caught out. A spreadsheet showing strong nightly rates is not what the lender uses.
Two published examples show the approach:
- Cumberland’s January 2026 holiday-let criteria require annual net rent, after a 20% deduction for letting costs, to cover 145% of a stressed interest figure. For fixes under five years the stress rate is the higher of 5.5% or the product rate plus 2%. Five-year fixes use the product rate.
- Leeds Building Society says its valuers independently verify the rental income. It assesses holiday-let affordability using seasonal rental income, an interest cover ratio and a stressed interest rate.
The practical lesson is that mortgageable rent is usually lower than headline turnover. Operating costs are deducted, seasonal dips count, and a stress rate sits above the real rate. These are examples from two lenders, and others will differ.
A simple worked example
Take a hypothetical property that the valuer says will bring in £30,000 of rent a year. Under a test like Cumberland’s, a 20% letting-cost deduction leaves £24,000. Whether that is enough then depends on the loan size and the stress rate, because the £24,000 must cover 145% of the stressed interest. A smaller loan passes more easily than a larger one on the same property. This is an illustration of the method, not a prediction for your property.

Deposits, rates and fees
Lenders in this area commonly want a bigger deposit than for a standard let. One specialist lender lists a 75% maximum loan to value, a £199 application fee and a requirement to evidence the deposit and its source, with extra due diligence where funds come from a third party or overseas. Proving the deposit is part of underwriting, not a conveyancing afterthought. If you are self-employed, our guide to proving your deposit as a self-employed applicant covers the paperwork. Our page on holiday let mortgage deposits in East Sussex covers a closely related product.
For a sense of pricing, one specialist lender’s March 2026 range listed serviced accommodation two-year fixed rates from 5.54% and five-year fixed rates from 6.04%, both at 75% LTV. It showed arrangement fees of 2% or 5% and a revert rate of base rate plus 5.00%. These are a snapshot, not an offer, and what you are offered depends on your circumstances and the lender’s criteria.
Budget for more than the interest:
- Stamp duty: in England and Northern Ireland the additional property surcharge is 5 percentage points above standard residential rates, while Wales and Scotland use their own taxes.
- Legal fees and valuation.
- Arrangement or application fees.
- Furnishing and fit-out.
- Insurance that specifically covers short-term letting.
What to have ready
Lenders will usually ask for a mix of the following, depending on how you are set up:
- Three months of bank statements.
- SA302s, tax year overviews or company accounts if you are self-employed or a director.
- Proof of the deposit and where it came from.
- A schedule of any properties you already own.
- A realistic income projection and a management plan.
- Furnishing costs and, if relevant, planning documents.
- An EPC.
If you work in construction, the CIS side matters too. Some lenders may use gross CIS earnings when assessing affordability, subject to their criteria. That does not raise your actual income and does not guarantee higher borrowing. Our buy-to-let minimum income guide explains how income thresholds can come into play.
Planning, lease and insurance checks
Getting the mortgage is only part of it. Before you commit, work through these checks:
- Planning. In London, short-term accommodation is generally limited to 90 nights in a calendar year without planning permission, and going over needs local permission. Outside London, ask the local council whether your letting pattern needs consent.
- The lease. If the property is leasehold, read the covenants. A requirement to use the home as a private residence has been held to prohibit short-term lets. A solicitor should confirm this before you exchange.
- Permissions. The same London guidance advises getting permission from the landlord, freeholder, mortgage provider and insurer, and checking guest safety and fire risks.
- Insurance. Home insurance exclusions for short lets can themselves put you in breach of mortgage terms, so confirm that cover matches how you let.
- Resale appeal. One lender says acceptable short-term-let properties must appeal to both owner-occupiers and investors, and valuers check this.
For planning and lease questions, take advice from a solicitor or planning professional. A mortgage adviser can tell you what lenders will accept, but not whether your lease or planning status allows the use.
How we help
We are a local broker serving Hastings, Eastbourne, Hailsham, Bexhill-on-Sea and the rest of East Sussex, and we are available to talk through your plans. Our services include buy-to-let and limited company mortgages, and we work with self-employed clients, CIS subcontractors, company directors and landlords. We explain the options, costs and risks so you can decide with a clear picture.
If you want to know what you could borrow before you start viewing, we offer a mortgage affordability assessment and capacity report for a one-off £199.00. Contractors who own or plan to buy property may also want to look at our CIS subcontractor mortgages and self-employed and company director mortgages pages.
Our view
Serviced accommodation attracts a lot of enthusiasm and not much clear explanation. The mortgage is rarely the hard part. The hard part is matching the way you intend to let with a lender whose criteria actually allow it, and knowing in advance how that lender will count your income.
We start with your circumstances: how you are paid, what deposit you have, what you already own, and how you plan to run the property. For self-employed applicants and CIS subcontractors, how a lender treats your income can change the picture, and we explain that plainly without promising any outcome.
Our aim is for you to understand the costs and risks before you apply, and to have support from the first enquiry through to completion and your later reviews.
Paul McMath CeMAP CeRER
FAQ
Can I use a standard buy-to-let mortgage for serviced accommodation?
Usually not without the lender’s consent. Standard buy-to-let terms typically restrict the property to a longer residential tenancy, and short lets without permission can breach the conditions. Some lenders have products designed for short-term letting, so the right route is to choose a mortgage that allows it from the start.
How much deposit do I need?
It varies by lender and by your circumstances. Specialist ranges often lend up to around 75% of the value, which means a deposit of at least 25%, and you will need to show where the deposit came from. We can tell you what is realistic for your situation.
Will lenders use my expected nightly income?
Not as headline turnover. Lenders typically use verified rent, deduct costs, apply an interest cover ratio and stress the interest rate. That is why a profitable-looking projection may support a smaller loan than you expect.
Can I get one if I am self-employed or a CIS subcontractor?
Yes, applicants like you can apply, and it is a large part of our work. Lenders will want evidence of your income, such as SA302s or accounts. Some may use gross CIS earnings in affordability, subject to their criteria, but that does not guarantee a higher loan.
Talk to a local adviser
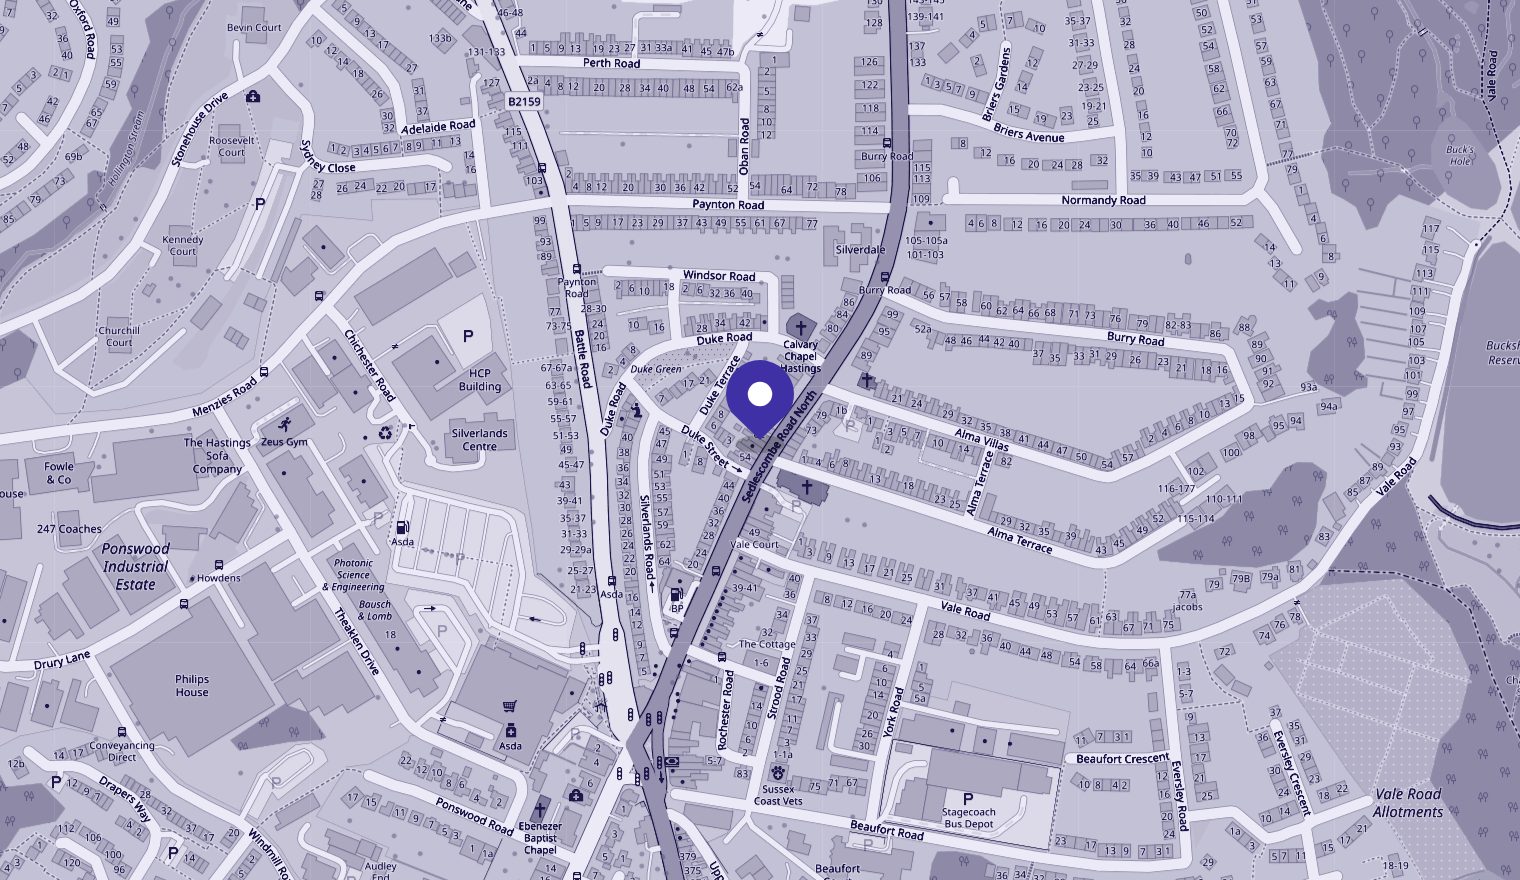
If you are considering serviced accommodation, or want to see whether your current mortgage allows it, contact Prosper Home Loans at 60 Sedlescombe Road North, St. Leonards-on-Sea, TN37 7DT. We will go through your options and what lenders may ask for.
Sources
- Swansea Building Society: holiday let mortgages
- Foundation Home Loans: short term let, holiday let and serviced accommodation
- Cumberland: holiday let criteria guide, January 2026
- Leeds Building Society: mortgage lending criteria and guidance
- West One: buy-to-let quick criteria guide
- HTB: specialist mortgage interest rates
- Property Tax Partners: stamp duty on a holiday let
- London City Hall: short term and holiday lets guidance
- DRK Planning: serviced accommodation and planning use classes
- Addleshaw Goddard: Airbnb and mortgages
Recommended
- Commercial Investment Mortgages in the UK: How They Work
- Owner-Occupied Commercial Mortgages: How They Work in the UK
- UK JBSP Mortgages: Who Owns the Home, Who Owes the Debt?
- Interest-Only vs Repayment Mortgages: Which Suits You?
This article provides general information and is not a personal mortgage recommendation. Mortgage availability and eligibility depend on your circumstances and lender criteria. Rates and criteria can change. We will explain any applicable fees before you commit. Think carefully before securing other debts against your home. Consolidating debts over a longer term may reduce your monthly payments but increase the total amount you repay. Your home may be repossessed if you do not keep up repayments
