£62,057 average: Equity release costs for UK 55+ home improvements
Yes, equity release can pay for home improvements, and it is one of the most common reasons homeowners aged 55+ apply for it. But it is a long-term loan, not free money: compound interest and fees can shrink your estate significantly over 10 to 30 years, it can affect means-tested benefits, and by law you must take regulated financial advice before proceeding.
TL;DR:
- Fees for advice, valuation, legal services, and lender charges are deducted from the released funds, significantly reducing the amount available for renovation work.
- Compound interest can cause the loan balance to double or triple over 10 to 30 years if interest is not paid regularly, especially at higher interest rates like 6% or 7%.
- Equity release can impact means-tested benefits, meaning homeowners should model the effects before proceeding and consider staged drawdowns to minimize benefit loss.
- Alternatives like remortgaging, personal loans, savings, or grants are often cheaper or more suitable, and regulated advice is legally required before any equity release plan is approved.
Table of Contents
- How does equity release work for home improvements?
- How much could you release for renovations?
- What does equity release cost, and how fast does interest grow?
- Will equity release affect my benefits or tax position?
- Are there better alternatives to equity release?
- How do you prepare for an equity release application?
- Budgeting the renovation once funds are released
- Why regulated advice matters, and how Prosperhomeloans can help
- An adviser’s honest take on using equity release for renovations
- Get tailored equity release advice from Prosperhomeloans
- Sources
- FAQ
How does equity release work for home improvements?
Two products sit under the “equity release” umbrella, and they work very differently. A lifetime mortgage is by far the more common route: you borrow against your home’s value while retaining ownership, and the loan (plus interest) is repaid when you die or move into long-term care. A home reversion plan means selling part or all of your home to a provider in exchange for a lump sum or income, while retaining the right to live there rent-free. Home reversion plans have declined in popularity in the UK market, largely because they involve giving up outright ownership.
Within a lifetime mortgage, you typically choose between:
- Lump sum: you take the full amount agreed in one go, useful for a single big project like an extension.
- Drawdown facility: you release an initial amount and keep a reserve to draw down later, only paying interest on what you actually take.
- Payment-term or interest-serviced options: you pay some or all of the monthly interest yourself, slowing the growth of the debt.
For renovation projects, the choice matters more than most homeowners realise. A single-storey extension with one contractor and one payment schedule often suits a lump sum. Staged works, such as a kitchen this year and a bathroom next year, tend to suit drawdown better, because drawdown facilities are increasingly popular for staged renovations precisely because they avoid interest accruing on money still sitting unused in an account.
How much could you release for renovations?
Lenders calculate how much you can release using loan-to-value bands linked to your age. Broadly, the older you are, the higher the percentage of your property’s value you can typically access, because lifetime mortgage pricing reflects life expectancy. A homeowner in their late 60s might access a meaningfully higher percentage than someone at 55, though exact figures vary between lenders and depend on health and property type too.
In numbers: Home improvements account for around 20 to 21% of all equity release funds drawn in recent years, and average sums released for renovations sit around £62,057, according to SunLife data reported by Unbiased.
That average masks huge variation by project type:
- Bathroom adaptations (walk-in showers, grab rails, stairlifts): often £5,000 to £15,000, frequently funded by a smaller drawdown release.
- Kitchen refits: typically £15,000 to £30,000, sitting comfortably within a modest lump sum.
- Single-storey extensions: commonly £40,000 to £80,000 or more, which is where the national average for improvement-focused releases tends to land.
Eligibility usually requires you to be at least 55, own a property worth a minimum threshold (often around £70,000 to £100,000 depending on the lender), and use it as your main residence. Any existing mortgage balance is normally cleared from the released funds first, which reduces what is left over for the actual building work.
What does equity release cost, and how fast does interest grow?
Arranging a lifetime mortgage brings several fees, most of which are commonly deducted from the amount you release rather than paid upfront in cash:
- Advice fee charged by your broker or adviser for the regulated advice you are legally required to receive.
- Valuation fee for the property survey the lender needs.
- Solicitor’s fee to handle the legal side, including independent legal advice you must take.
- Lender’s arrangement or completion fee, which varies by product.
Homeowners frequently underestimate how much these combined fees reduce the cash actually available for building work, since they are taken from the release before a contractor sees a penny.
The bigger cost, though, is compound interest. Which?'s scenario modelling shows a lifetime mortgage balance can double or more over 10 to 30 years if no interest is ever paid down. A rough rule of thumb, the “rule of 72,” illustrates this well: divide 72 by the interest rate to estimate how many years it takes the debt to double. At a 6% rate, that is roughly 12 years; at 7%, closer to 10 years. Left untouched for 25 or 30 years, a £62,057 release could realistically balloon several times over.
Pro Tip: Ask whether your chosen plan allows voluntary partial repayments without penalty. Even paying off a small amount of interest each month, if you can afford it, meaningfully slows how fast the balance compounds.
Payment-term lifetime mortgages, where you service some or all of the interest monthly, are the clearest way to limit this growth, alongside choosing drawdown so you are not paying interest on unused funds sitting idle.
Will equity release affect my benefits or tax position?
Releasing a lump sum changes your capital position overnight, and that matters if you receive means-tested support.
- Pension Credit, Universal Credit and council tax reduction are all capital-sensitive. Gov confirms capital above set thresholds reduces or removes entitlement, so a large cash release can push you over the line even temporarily.
- Capital gains tax rarely applies to your main home, but it can matter if you later sell a second property or move released funds into other investments.
- Inheritance tax planning also needs revisiting, since equity release reduces the value of your estate, which can cut both ways depending on your circumstances.
Released capital sitting in a bank account, even briefly while contractors are paid in stages, can be assessed against benefit thresholds exactly the same as capital you’ve had for years.
The safest approach is modelling the effect on your specific benefits before signing anything, and considering a smaller, staged drawdown rather than one large lump sum if you are close to a means-tested threshold.
Are there better alternatives to equity release?
Age UK’s own guidance is blunt on this point: equity release should generally be treated as a last resort, with other routes explored first.
- Remortgaging is often cheaper if you can pass a lender’s affordability and income checks, though age and retirement income limits catch many older applicants out. Remortgaging to release equity is worth ruling in or out before considering a lifetime mortgage, since fees are typically lower and you keep full ownership.
- Personal loans or second-charge loans suit smaller projects, such as a boiler replacement or roof repair, where you don’t want to disturb your main mortgage.
- Savings remain the cheapest option for modest, essential repairs, with no interest at all.
- Grants and Home Improvement Agency support can fund accessibility adaptations, sometimes fully, particularly for disabled or vulnerable homeowners, and are frequently overlooked.
How do you prepare for an equity release application?
Bring the right paperwork and the process moves considerably faster.
- Proof of ID and address, your most recent mortgage statement, and property title details.
- Contractor quotes for the planned works, even provisional ones, to show how funds will be used.
- A recent utility bill and details of any existing debts or loans secured against the property.
Ask any adviser directly: what are the total fees, is the lender an Equity Release Council member offering the no negative equity guarantee, what are the early repayment charges, and can the plan be ported if you move home later?
Pro Tip: Get contractor quotes before your advice appointment, not after. It gives your adviser a real figure to model against rather than a guess.
Timelines typically run six to ten weeks from first advice meeting to funds landing in your account, with valuation and solicitor turnaround the most common causes of delay.
Budgeting the renovation once funds are released
Equity release tends to deliver the best value on work that either protects the property or the person living in it: energy efficiency upgrades, walk-in showers and stairlifts, and structural repairs like roof or damp work that would only get more expensive if left.
- Build a written budget that separates labour, materials, VAT, and a contingency of at least 10 to 15%.
- Match drawdown releases to contractor payment milestones rather than releasing everything at once.
- Vet contractors through references and, where possible, a trade body such as FMB or TrustMark before signing anything.
Pro Tip: Keep your contingency fund untouched until the final week of the project. Cost creep almost always shows up at the end, not the start.
Staged drawdown, matched to milestones, keeps interest accruing only on money actually spent, and it stops a single quoting error from turning into a second borrowing round six months later.
Why regulated advice matters, and how Prosperhomeloans can help
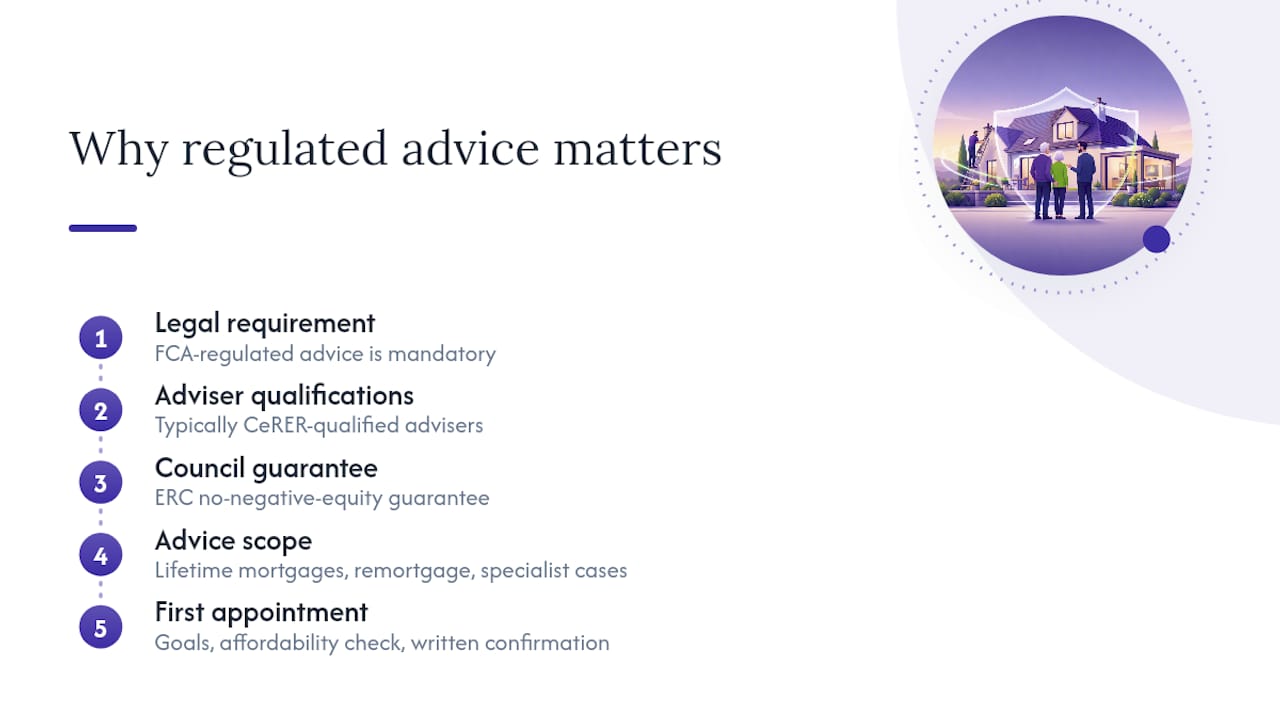
To take out a lifetime mortgage without regulated advice isn’t just risky, it’s not legal. Every equity release plan in the UK must go through FCA-regulated advice, typically from a CeRER-qualified adviser, and reputable lenders belong to the Equity Release Council, whose no negative equity guarantee means you will never owe more than your home is worth.
Independent, whole of market mortgage advice covers lifetime mortgages, remortgaging as an alternative, and specialist cases including contractor mortgages, CIS voucher mortgages for enhanced self-employed income, and debt consolidation mortgages. A first appointment covers your goals, an affordability check, and written confirmation of what’s realistically achievable before you commit to anything.
An adviser’s honest take on using equity release for renovations
Used sensibly, equity release for renovations makes the most sense for safety, accessibility, and energy work that genuinely protects the home and the person living in it. Consider staged drawdown over one large lump sum, and have the inheritance conversation with family early rather than after the paperwork is signed. If remortgaging or a modest personal loan covers the project affordably, favour that route first.
— Paul
Get tailored equity release advice from Prosperhomeloans
Prosperhomeloans is the local alternative to guesswork when it comes to funding home improvements from your property’s equity. As independent, whole of market advisers covering Hastings, Eastbourne, Hailsham and Bexhill-on-Sea in East Sussex, and available seven days a week, we model lifetime mortgages, remortgage-to-release options, and debt consolidation mortgages side by side, so you see the real cost difference before committing.
A first appointment with a CeMAP/CeRER-qualified adviser covers your renovation goals, an affordability check, and written confirmation of what’s realistically available to you. We also support specialist cases, including CIS voucher mortgages for self-employed contractors and dedicated contractor mortgages where standard income checks don’t reflect your real earnings. Bring your recent mortgage statement and any contractor quotes to your appointment, and we’ll model your options properly. Explore our lifetime mortgage services or remortgaging options to book a conversation.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- When is equity release worth it? - Which?
- Equity release factsheet - Age UK
- How can I release equity for home improvements? | Unbiased
- Gov
FAQ
What does Martin Lewis say about equity release?
Martin Lewis has consistently urged caution, describing equity release as a decision that should only follow independent financial advice and full comparison against alternatives like downsizing or remortgaging. His guidance echoes Age UK’s position that it’s best treated as a last resort rather than a first option.
What is the typical cost of equity release in the UK?
Costs include an advice fee, a valuation fee, a solicitor’s fee, and a lender arrangement fee, most of which are usually deducted from the released sum. The real long-term cost is compound interest, which Which?'s modelling shows can double a loan balance over 10 to 30 years if left unpaid.
Is there a better alternative to equity release?
For homeowners who can meet a lender’s affordability checks, remortgaging is usually cheaper and avoids compounding interest on unpaid amounts. Grants, Home Improvement Agency support, savings, and personal loans should also be ruled out first for smaller projects.
Is equity release a good idea for funding home improvements?
It can be, particularly for safety, accessibility, or energy-efficiency work, but it needs careful modelling against your benefits, inheritance wishes, and alternatives. Regulated advice from an FCA-authorised, CeRER-qualified adviser, such as those at Prosperhomeloans, is a legal requirement before any plan proceeds.
How much can I typically release for home improvements?
Amounts vary by age and property value, but average releases for home improvements sit around £62,057, with smaller adaptations needing far less and extensions often needing considerably more. A written illustration from a regulated adviser is the only reliable way to know your own figure.
Recommended
